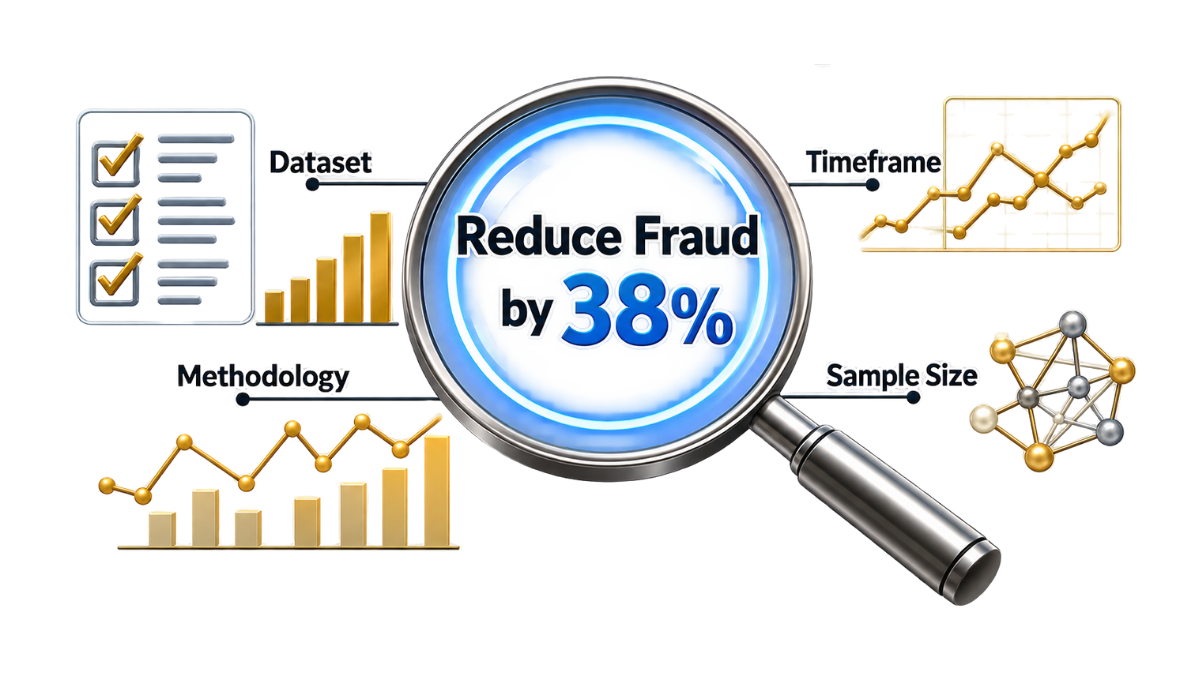
Your highest-converting claims are often the ones that deserve the most scrutiny.
A fintech homepage rarely contains outright falsehoods.
But it often implies outcomes that are not universal and savings that may not apply to every user, or automation that still requires manual steps.
And this is where misunderstandings begin.
Most of these claims are written with good intentions. They reflect real product capabilities and real customer experiences. The real problem is ambiguity.
When financial products are involved, ambiguity carries consequences. Marketing copy, blog content, advertisements, and sales materials are all interpreted as financial promotion under many jurisdictions’ financial promotion rules. That means the claims embedded in them are subject to the same scrutiny as formal product disclosures.
This is why fintech companies increasingly need a content claims policy-especially when building fintech content strategy frameworks that balance marketing growth with regulatory credibility.
The content claims policy’s purpose is to ensure that the statements a company makes about its product are clear, defensible, and supported by evidence.
When implemented properly, a claims policy does three important things:
- It protects the company from regulatory risk.
- It helps teams understand what can safely be said about the product.
- And it improves the credibility of the content itself.
In fintech, credibility is part of the product experience.
Before discussing how to build a claims policy, it helps to understand why fintech content requires one in the first place.
Why Fintech Content Needs a Claims Policy
Fintech marketing operates under a different standard than most SaaS content.
When a product handles payments, lending, investing, or financial data, the messaging around it can influence financial decisions. Because of this, regulators often treat website copy, advertisements, blog content, and sales materials as financial promotion.
In practice, this means the language used in marketing is subject to the same scrutiny as product disclosures.
Ambiguous claims about savings, automation, performance, security, or compliance can create expectations that extend beyond what the product consistently delivers. Over time, this creates operational friction inside the company.
Content may rank in search but cannot be reused confidently in sales conversations-which is why SEO content for fintech companies needs stronger claim validation.
. Legal teams step in late to rewrite messaging. Writers struggle to understand what is acceptable language, which leads to either cautious copy or claims that later need to be softened.
In fintech, marketing copy becomes part of the company’s risk surface.
Definition: Fintech Content Claims Policy
A fintech content claims policy is a documented framework that defines how product claims can be written, supported, qualified, and approved across marketing channels.
It ensures that statements about performance, cost, security, or outcomes remain accurate, verifiable, and contextually clear.
When teams operate without this structure, claims tend to drift between marketing ambition and compliance caution. A claims policy exists to align both.
What Counts as a “Claim”
A content claim is any statement or element that shapes a user’s expectation about a product’s capability, performance, outcome, or benefit.
Claims appear throughout a fintech website in places that are not always recognized as claims.
They include:
- Headlines and subheadings
- Statistics such as “38% reduction in fraud”
- Descriptive words such as “faster,” “smarter,” “automated,” or “compliant.”
- Customer testimonials and case studies
- Product screenshots that imply functionality
- Comparison tables showing advantages over competitors
- Calls-to-action that suggest ease or speed
Each of these elements communicates an expectation about the product.
For example, describing a platform as “automated” suggests a level of independence from manual work. A testimonial describing dramatic savings implies similar results may be achievable for other customers. Even a product screenshot can imply capabilities that depend on specific configurations or conditions.
Because of this, claims often appear indirectly rather than explicitly.
The riskiest claims are usually the ones no one realized were claims.
A content claims policy begins by recognizing that expectations are shaped not only by what a company says directly, but also by what the surrounding content suggests.
The 5 Fintech Claim Types That Create the Most Risk
Not all marketing claims carry the same level of risk.
Some statements simply describe product availability or features. Others imply measurable outcomes or regulatory status. The latter tend to attract far greater scrutiny from regulators, compliance teams, and experienced buyers.
In fintech content, certain types of claims consistently create the most regulatory and credibility challenges. These claims shape expectations about outcomes, savings, security, or reliability. If they are not supported with clear evidence and context, they can easily be interpreted as guarantees.
Understanding these categories helps teams identify where stronger evidence and clearer qualifiers are required.
In practice, fintech claims tend to fall into three broad risk levels, depending on the expectations they create.
High-Risk Claims
High-risk claims usually imply measurable outcomes or regulatory status. These claims attract the most scrutiny because they can influence financial decisions.
Performance Claims
Performance claims describe measurable improvements or outcomes produced by a product.
Examples include statements such as:
- “Reduce fraud by 38%”
- “Increase approval rates”
- “Improve payment success rates”
These claims are sensitive because they imply outcomes that appear measurable and repeatable.
If the supporting evidence is unclear, users may assume the result applies broadly across all customers or situations.
Policy rule
Performance claims should always be supported with:
- the dataset used
- the timeframe of the analysis
- the methodology applied
- the sample size behind the result
This context clarifies whether the claim reflects a broad pattern or a specific case.
Savings or Cost Claims
Savings claims describe financial benefits such as reduced fees or operational cost improvements.
Examples include:
- “Save 5% on spend”
- “Lower processing fees”
The risk with these claims is that users often interpret them as guaranteed outcomes. In reality, savings usually depend on variables such as transaction volume, geography, or product configuration.
Policy rule
Savings claims should include clear qualifiers such as:
- “on average”
- “up to”
- contextual details explaining who experienced the savings and under what conditions
Providing this context helps prevent users from assuming universal results.
Security and Compliance Claims
Security and compliance statements are among the most sensitive claims in fintech marketing and should always be reviewed against relevant financial marketing compliance guidance.
Examples include phrases such as:
- “Fully compliant”
- “Enterprise-grade security”
These claims function as trust anchors. When they are vague or overstated, they can create expectations that are difficult to support.
Policy rule
Avoid broad or absolute wording.
Security claims should specify:
- the security standard or certification
- the geographic or regulatory scope
- the systems or processes covered by the claim
Specificity helps users understand exactly what protection or compliance actually means.
Medium-Risk Claims
Medium-risk claims typically relate to usability, onboarding speed, or automation. They are less likely to trigger regulatory scrutiny but can still create expectation gaps.
Speed or Automation Claims
Speed and automation claims describe how quickly a product can be implemented or how much work it removes from a process.
Examples include:
- “No integration required”
- “Get started instantly”
These claims can become misleading when they overlook onboarding requirements, configuration steps, or edge cases that apply to certain users.
Policy rule
Before using these claims, teams should ask:
- Is this statement accurate for all users?
- What steps are required before the product actually works?
- What assumption will a user make when they read this claim?
Answering these questions helps ensure that convenience claims do not hide operational complexity.
Social Proof Claims
Social proof signals include testimonials, ratings, and statements about adoption.
Examples include:
- “Trusted by leading fintech companies”
- Customer testimonials describing results
- High product ratings or review counts
These claims can create risk when they imply outcomes that are not representative of the typical user experience.
Policy rule
Social proof claims should be reviewed for:
- whether the customer was compensated or incentivized
- whether the example reflects a typical user outcome
- whether the context of the testimonial is clear
Providing transparency ensures that social proof reinforces credibility rather than creating misleading expectations.
Low-Risk Claims
Low-risk claims describe objective, verifiable facts about the product. These statements rarely create misleading expectations because they do not imply financial outcomes or performance improvements.
Factual or Availability Claims
Factual or availability claims describe objective product information such as geographic coverage, supported features, or system capabilities.
Examples include statements such as:
- “Available in 197 countries”
- “Supports 135+ currencies”
- “Includes subscription billing tools”
These claims generally carry lower risk because they describe verifiable facts rather than outcomes or financial impact.
However, inaccuracies can still create credibility problems if the information is outdated, incomplete, or overstated.
Policy rule
Factual claims should always be:
- Accurate and verifiable
- Consistent with product documentation
- Updated when product capabilities change
- Linked to a clear source where possible
Maintaining accuracy ensures that factual claims remain reliable and do not unintentionally mislead users.
What Regulators Actually Care About
Fintech teams often assume that compliance rules are highly technical or difficult to interpret. In practice, most regulatory expectations follow a few simple principles.
Across jurisdictions, regulators tend to evaluate marketing claims through three core questions.
1. Can you prove what you say?
If a company makes a measurable claim about performance, savings, or results, regulators expect the claim to be supported by evidence.
This evidence may include internal data, research methodology, or documented results from a defined group of users. The key requirement is that the claim can be substantiated if someone asks for proof.
2. Could the claim mislead a reasonable user?
A statement does not need to be explicitly false to create a problem. Messaging can become misleading through implication, exaggeration, or lack of context.
If the average reader is likely to interpret a claim in a way that overstates the product’s capability, regulators may treat the statement as misleading even if the wording is technically accurate.
3. Does the content show the full picture?
Financial promotion should not highlight benefits while hiding relevant limitations or risks.
When a claim describes savings, automation, performance, or compliance, the surrounding content should also clarify the conditions under which the claim applies.
In fintech, omission can be just as misleading as exaggeration.
The Anatomy of a Fintech Content Claims Policy
A claims policy works best when it functions as an operational system rather than a loose set of guidelines – similar to how structured fintech content systems manage messaging across marketing channels. The goal is to give teams clear rules for how claims are written, reviewed, and maintained across all marketing channels.
A practical fintech claims policy usually includes the following components.
1. Scope
The policy should apply to all customer-facing communication, not just website copy.
This typically includes:
- Website pages
- Blog articles
- Advertisements
- Email campaigns
- Sales presentations and decks
- Social media content
Claims often travel between these channels. Defining the scope ensures that messaging remains consistent wherever the product is discussed.
2. Claim Classification System
Not every claim requires the same level of scrutiny. A simple classification system helps teams determine how much validation is required before publishing.
| Level | Meaning | Example |
|---|---|---|
| Green | Safe factual statements | “Available in 197 countries” |
| Yellow | Needs validation or clarification | “Faster onboarding” |
| Orange | Requires supporting evidence and review | “Reduce fraud by 38%” |
| Red | Not permitted | “Guaranteed returns” |
This structure allows low-risk statements to move quickly while ensuring higher-risk claims receive proper review.
3. Evidence Requirements
Any measurable claim should be backed by documented evidence.
A typical policy requires teams to record:
- the data source supporting the claim
- the owner responsible for the data
- the timeframe the data covers
- the methodology used to calculate results
- the approval record confirming internal validation
This ensures that claims can be substantiated if questions arise.
4. Required Qualifiers
Many fintech claims require contextual language to prevent misinterpretation.
Common qualifiers include phrases such as:
- “on average”
- “up to”
- “for eligible users”
- “results may vary”
These qualifiers help clarify the conditions under which the claim applies.
5. Prohibited Wording
Certain phrases tend to create unrealistic expectations and are often restricted within fintech claims policies.
Examples include:
- “guaranteed”
- “risk-free”
- “fully compliant”
- “instant approval”
- “best” (without a defined benchmark)
Prohibiting vague absolutes helps reduce ambiguity and encourages more precise language.
6. Review Workflow
A clear review workflow prevents bottlenecks and ensures accountability.
A common structure looks like this:
Writer → Channel owner → Product or data owner → Compliance → Publish
The classification system can guide how quickly claims move through this process:
- Green claims → fast publishing
- Yellow claims → owner validation
- Orange claims → compliance review
- Red claims → rejected or rewritten
This approach keeps the review process structured without slowing down marketing unnecessarily.
7. Claims Register
One of the most valuable components of a claims policy is a centralized claims register.
This document acts as a reference library for approved claims and typically includes:
- the approved claim text
- supporting evidence
- the internal owner responsible for the data
- the approval date
- an expiration or review date
This system prevents teams from repeatedly revalidating the same claims and ensures that messaging remains consistent across channels.
A useful way to think about this system is simple:
Your claims should be version-controlled like product code.
8. Revalidation System
Claims should not remain static indefinitely.
Data changes, products evolve, and regulatory expectations shift over time. A claims policy should therefore include a regular review cycle.
Many companies schedule claim reviews on a quarterly or biannual basis to confirm that the supporting data remains accurate.
This process ensures that marketing content continues to reflect the current state of the product.
Real Fintech Examples
Claims policies become easier to understand when applied to real examples. Many fintech websites contain strong marketing statements that communicate value clearly but also require careful framing to remain defensible.
Looking at these claims through a policy lens helps reveal the questions a team should ask before publishing them.
Example 1: “Reduce Fraud by 38%”
What’s happening
This is a strong performance claim. It presents a precise numerical improvement that signals measurable product impact.
Policy lens
Before publishing a claim like this, several questions need clear answers:
- Where did the 38% figure come from?
- Across which users or customers was the result measured?
- Over what period of time was the data collected?
Lesson
This can be an excellent claim when supported by evidence. Without context, however, users may assume the result applies universally.
Example 2: “No Integration Required”
User assumption
A reader may interpret this as meaning the product works immediately without technical setup.
Reality
In many cases, some level of configuration, data connection, or onboarding step is still required.
Policy lens
Claims like this should be reviewed for hidden assumptions. If certain integrations or configurations are still necessary, the language may require clarification or qualification.
Example 3: “Average Savings of 5%”
Risk
Savings claims can easily sound like guaranteed outcomes.
A user reading this statement may assume the savings will apply directly to their situation.
Policy lens
Teams should ask:
- What sample size produced this average?
- How were the savings calculated?
- What conditions made the savings possible?
Providing context prevents the claim from implying a guaranteed financial benefit.
Example 4: Automation Claims
Example statement:
“Expenses categorize themselves.”
Policy lens
Automation claims often simplify how a system works.
Questions worth asking include:
- How often does automation require manual correction?
- Are there exceptions where categorization fails?
- Does accuracy depend on specific user behavior or data quality?
Automation messaging works best when it acknowledges that edge cases may exist.
Example 5: “Compliant Worldwide” (Testimonial)
Risk
Statements like this often appear in testimonials or marketing quotes. However, they can imply universal regulatory compliance across jurisdictions.
Policy lens
Compliance claims require careful framing.
Important questions include:
- Which regulations or standards are being referenced?
- In which regions does the claim apply?
- Is the statement describing a customer’s experience rather than a verified capability?
Providing context helps prevent the testimonial from suggesting broader compliance than the product actually supports.
How to Implement This Without Slowing Marketing Down
Many teams assume that introducing compliance rules will slow content production. In practice, the opposite tends to happen.
The real bottleneck is usually the absence of structure.
When teams operate without a claims policy, the same issues repeat across projects. Writers produce copy that later requires heavy revision. Legal reviews happen late in the process, forcing last-minute edits. Claims are softened repeatedly because no one is certain what language is acceptable.
Over time, this creates a cycle of delays and diluted messaging.
A structured claims policy changes how decisions are made. Instead of reviewing every statement from scratch, teams work within a set of predefined rules.
Without a claims policy, teams typically face:
- repeated rewrites during legal review
- unclear boundaries around acceptable claims
- vague language used to avoid risk
- marketing statements that lose impact
With a claims policy in place, the process becomes more predictable:
- pre-approved claim categories create clear publishing lanes
- evidence requirements are known in advance
- review workflows become faster and more consistent
- stronger claims can be published with confidence
The goal is not to restrict marketing but to remove uncertainty from the writing process so teams can move faster without increasing risk.
A good claims policy makes the messaging more precise and far more difficult to challenge.
A Simple Fintech Claims Policy Template
Before publishing any claim, teams can use a short checklist to evaluate whether the statement is clear, defensible, and properly supported.
This checklist helps translate the claims policy into a practical step during content creation.
Before publishing any claim, ask these simple questions:
- Is this claim measurable or implied?
- Do we have evidence that supports it?
- Is the scope of the claim clearly defined?
- Could a user reasonably misinterpret what this means?
- Are qualifiers needed to provide context?
- Does this claim require review from product, data, or compliance teams?
- Has the approved version been recorded in the claims register?
Using a checklist like this helps teams catch potential issues early in the writing process. Instead of correcting claims after publication, the evaluation happens before the content goes live.
Over time, this simple habit strengthens both the credibility and the consistency of fintech marketing content.
Frequently Asked Questions
What is a fintech content claims policy?
A fintech content claims policy is simply a set of internal rules for how marketing claims should be written, supported, and approved.
It helps teams make strong statements about the product while ensuring those statements are accurate, defensible, and supported by evidence.
Instead of guessing what language is acceptable, writers, marketers, and product teams work within a shared framework.
Why do fintech companies need a claims policy?
Because fintech marketing operates under a different level of scrutiny.
When a product handles payments, lending, investing, or financial data, the messaging around it can influence real financial decisions. That means website copy, ads, blog content, and sales materials can all be treated as financial promotion.
A claims policy helps companies communicate clearly without accidentally promising more than the product consistently delivers.
What actually counts as a marketing claim?
More than most teams realize.
A claim is any statement that shapes what a user expects from the product.
That includes:
- headlines and product descriptions
- statistics and performance metrics
- testimonials or case studies
- product screenshots
- comparison tables
- even words like faster, automated, or secure
Often the riskiest claims are the ones that appear indirectly.
Which types of claims are the most sensitive in fintech?
Claims that suggest financial impact or measurable results tend to carry the most risk.
Examples include:
- performance claims such as fraud reduction percentages
- savings claims that imply cost improvements
- security or compliance statements
These statements can strongly influence user trust, which is why they usually require clear evidence and careful wording.
How do teams support claims with evidence?
Most companies treat claims the same way they treat product data.
If a statement describes a measurable result, teams should know:
- where the data came from
- what time period it reflects
- how the result was calculated
- how many users were included in the analysis
Documenting this information makes the claim easier to defend if someone asks how it was produced.
Won’t a claims policy slow marketing down?
In most cases, it does the opposite.
Without a clear policy, claims often go through multiple rewrites because teams are unsure what language is acceptable. Legal reviews happen late in the process and messaging becomes overly cautious.
A structured claims policy creates clear rules and approval paths, which actually makes it easier for teams to publish strong claims with confidence.
A Simple Next Step
If your fintech team produces a large amount of marketing content then it’s worth reviewing the claims those materials imply.
Many companies discover that their strongest marketing statements were never formally validated.
At Revnium, we help fintech companies review content claims, structure messaging frameworks, and ensure marketing statements remain defensible under regulatory scrutiny.
Learn how Revnium approaches fintech content strategy →
Final Thoughts
Fintech marketing operates in an environment where credibility matters as much as visibility.
Strong claims can attract attention, but attention alone does not build durable growth. What ultimately matters is whether those claims hold up when customers, partners, or regulators look more closely.
A structured claims policy helps teams make stronger statements without increasing risk. It replaces guesswork with clear rules, evidence, and shared understanding across marketing, product, and compliance teams.
Over time, this consistency builds something more valuable than persuasive copy: it builds trust.
Fintech does not reward the loudest claims. It rewards the ones that remain credible long after they are first published.
The goal is to say things that still hold up when someone looks closer.